March 11, 2025

Home-Related Tax Deductions

Tax season. Just the words can send shivers down your spine. But if you’re a homeowner, there’s a silver lining: potential savings! 


You’ve probably heard that you can deduct the interest you pay on your mortgage — but did you know there are many other ways homeowners can reduce their tax burden?


Before you start your return, read this post for common home-related tax deductions, eligibility requirements, and tips on how to maximize your savings.


Home-Related Tax Savings: The Basics


Before we get into the details, it’s important to define some important terms to set the stage.


Tax Deductions vs. Tax Credits


Most tax savings opportunities for homeowners come in the form of tax deductions. Deductions work by reducing your taxable income — essentially, the government allows you to subtract certain expenses from your total income before calculating how much you owe in taxes. This means a lower taxable income and, ultimately, a lower tax bill. For example, if you earn $50,000 and claim tax deductions worth $5,000, you will only pay taxes on $45,000. 


Tax credits, on the other hand, directly reduce your tax bill, rather than your taxable income. That means that if you owe $10,000 in taxes and claim a tax credit worth $2,000, your tax bill will be reduced to $8,000. 


Pro Tip: Meticulous record-keeping is crucial. Keep detailed records of all potentially eligible expenses. This will make tax time much smoother and ensure you don’t miss out on any deductions. 


Itemized Deductions vs. Standard Deduction


To understand what deductions apply to your situation, it’s important to know the difference between itemized deductions and the standard deduction. The standard deduction is a fixed dollar amount that you can subtract from your adjusted gross income (AGI) regardless of your actual expenses. Itemized deductions, on the other hand, are specific expenses that you can deduct, such as mortgage interest, property taxes, and charitable contributions.


You’ll need to choose whether to itemize or take the standard deduction. Generally, you should itemize if your total itemized deductions exceed the standard deduction. Most home-related deductions are only applicable if you choose to itemize.


2025 Standard Deduction Amounts


  • Single and Married Filing Separately: $15,000
  • Head of Household: $22,500
  • Married Filing Jointly: $30,0001


Source: IRS


Key Home-Related Tax Deductions and Credits


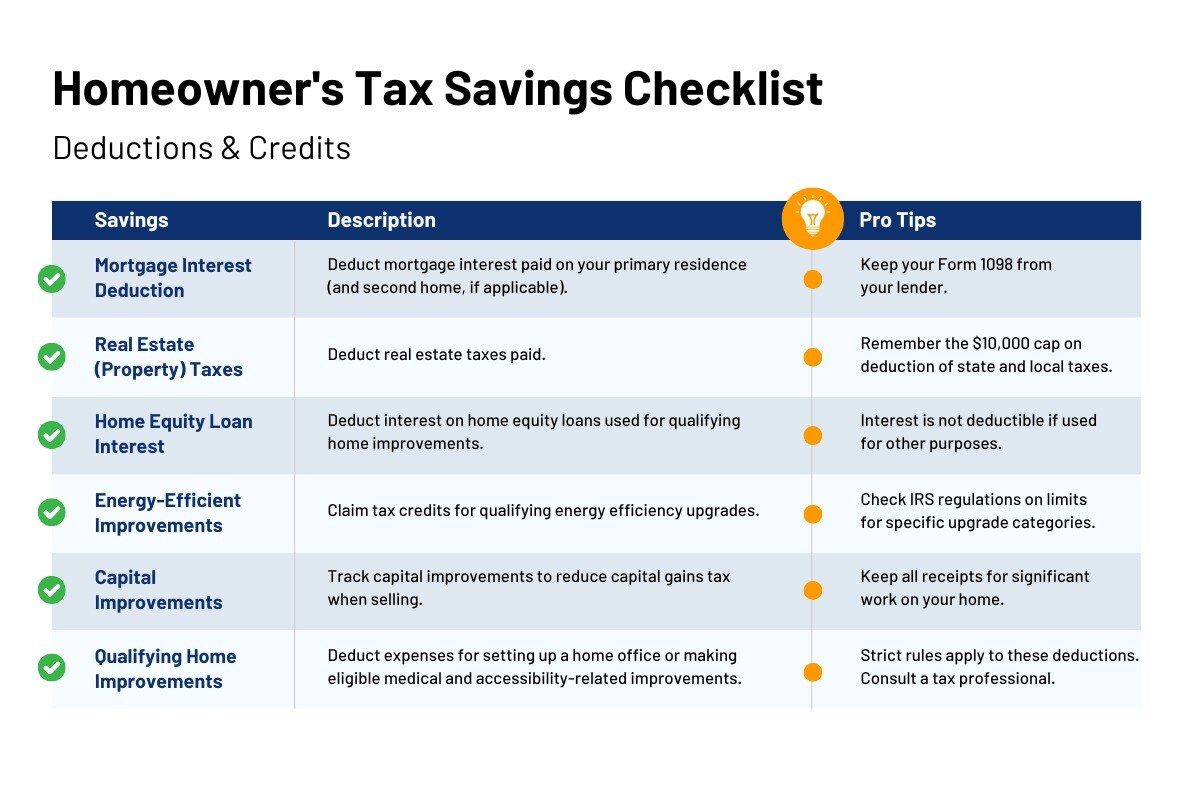
If you do choose to itemize your taxes, common tax deductions and credits available to homeowners include:


Mortgage Interest Deduction


No one likes to pay mortgage interest, but the good news is that you can deduct interest used to buy or build your primary residence or a second home. However, there are certain limitations that you need to be aware of.2


Mortgage size: If you file your taxes single or married filing jointly, you can deduct interest paid on the first $750,000 of mortgage debt3 for your primary residence or second home. If you are married but choose to file separately, that limit drops to the first $375,000 (for each partner). 


Requirements: 


  • The mortgage interest deduction only applies if your home is collateral for the loan (which is standard).
  • To qualify as a primary home, your property must have sleeping, cooking, and toilet facilities.
  • If you are deducting mortgage interest on a second home, you don’t need to use the home during the year; however, if you rent it out, you must spend at least 14 days or more than 10% of the days you rented it out (whichever is longer).


So, how do you calculate how much mortgage interest you’ve paid?


The amount of interest you pay each year will vary, even if your interest rate is fixed — that’s because mortgage amortization3 means that you pay more interest earlier in the mortgage’s term, and more principal closer to the end. Each year, your lender will send you (and the IRS) a copy of Form 1098, which shows how much you paid in interest.4


For example, let’s say you are a married homeowner filing jointly with a mortgage for $400,000. If your Form 1098 shows that you paid $25,000 in mortgage interest in 2025, you could deduct the full $25,000 from your 2025 household income. 


Real Estate Taxes (Property Taxes)


You can deduct state and local real estate taxes (property taxes) you pay on your primary residence or second home. However, it’s crucial to understand what qualifies. Only property taxes imposed for “general public welfare” are deductible5—if your town imposes a special assessment for a project that directly improves your property value, like a sewer line, that is not deductible. Furthermore, fees for local services, such as trash collection or sewer maintenance, are not deductible, even though your town may list them on the same bill as your property taxes.

There’s also a limit: the 2017 Tax Cuts and Jobs Act imposed a $10,000 cap on the total amount of 
state and local taxes (SALT)6 you can deduct. This includes state and local income tax (or sales tax) as well as property taxes. 


Finally, be aware that the amount you deduct must match the amount actually paid to the tax authority.7 This might differ from what you put into escrow if you pay property taxes through your mortgage lender. Typically, the amount your lender paid to your tax authority is listed on Form 1098. 


Home Equity Loan Interest


You can deduct the interest paid on home equity loans or home equity lines of credit, but with a significant caveat. Since 2017, that interest is only deductible if the loan proceeds are used to buy, build, or substantially improve3 your primary residence or second home, and the loan is secured by the home.

If you use the home equity loan for other purposes, such as a vacation, debt consolidation, or purchasing a car, the interest is generally not deductible. If you use part of the loan or line of credit for eligible purchases, and part for non-eligible purchases, only interest incurred on the portion used for eligible spending is deductible.


Loan interest is also not deductible if the funds are used for home improvement projects or repairs that do not “substantially improve” your home. Smaller projects, like repainting or new cabinets, likely do not qualify. However, projects like building an addition, a full kitchen remodel, or installing a new roof should qualify as substantial improvements.


It’s also important to note that home equity loan and HELOC interest rate deductions are subject to the same upper limits3 as mortgages (and are added together with your mortgage for calculation purposes). For example, if you have a $500,000 mortgage and a $300,000 home equity line of credit—which together exceed the $750,000 limit for a married couple—you would only be able to deduct interest paid on the first $750,000 of those combined loans. 


Home Improvement Expenses


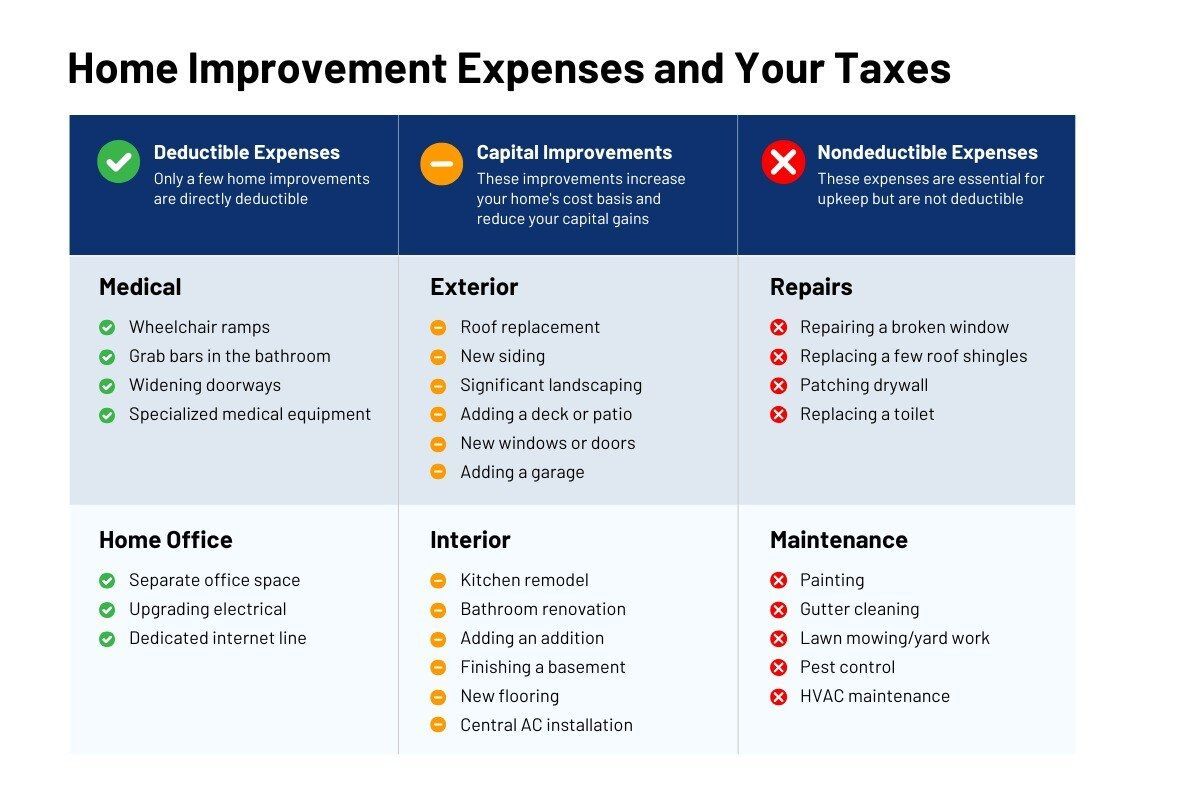
You can’t usually deduct home improvement expenses directly.9 However, the money you spend on capital improvements (improvements that increase your home’s value) can help reduce your tax bill later. These expenses are added to your home’s “cost basis,”10 which reduces your capital gains tax when you eventually sell the house. Think of it this way: by keeping records of your home improvements, you’re essentially increasing the “price” you’re considered to have paid for your home, thus lowering your profit when you sell. 


It’s important to note that not all projects qualify as capital improvement. Basic repairs and updates likely won’t qualify, while major additions and landscaping likely will (the considerations are the same as those used to determine whether home equity loan interest is deductible).

Beyond capital improvement, there are a few specific categories of home improvement that are deductible, including work on home offices (which is subject to specific limitations) and certain modifications for medical/accessibility reasons.
11

Energy-Efficient and Clean Energy Tax Credits


Certain energy-efficient home improvements can qualify you for valuable tax credits. Unlike deductions, which reduce your taxable income, tax credits directly reduce your tax bill, making them even more beneficial. 


For qualifying energy efficiency expenses in the 2024 tax year12, homeowners can claim up to 30% of qualified expenses on their federal tax return, with a maximum credit of $3,200.13 However, some qualifying expenses, like new exterior doors and windows, come with their own maximum credit limits, so it’s essential to check the specific rules. 


Another option is the Residential Clean Energy Tax Credit, which offers a 30% credit for the cost of installing renewable energy systems, such as solar panels, on your primary residence or a second home that you use part-time and don’t rent out.13 Many states also offer their own tax deductions, rebates, or credits related to energy efficiency and clean energy, so be sure to investigate what’s available in your state.


Selling Your Home and Taxes


When you sell your home, the difference between the selling price and what you originally paid for it (plus any major improvements) is called your capital gain. Think of it as your profit from the sale. Let’s walk through a simple example:


Imagine you bought your home for $200,000. Over the years, you invested in some significant upgrades, like a kitchen remodel ($30,000), a new roof ($15,000), and landscaping ($5,000). These are called “capital improvements,” and they increase your home’s “cost basis”—essentially, what the IRS considers you to have invested in the property. In this case, your adjusted cost basis would be $250,000 ($200,000 original price + $50,000 improvements).


Now, let’s say you sell your home for $350,000. Your capital gain would be $100,000 ($350,000 selling price – $250,000 adjusted cost basis).


Capital Gains Exclusion


The good news is that the IRS allows you to exclude a significant portion of your capital gain from taxation!14 If you’re single, you can exclude up to $250,000, and if you’re married filing jointly, you can exclude up to $500,000. To qualify for this exclusion, you need to have owned and used the home as your primary residence for at least two out of the five years before the sale. This is a key factor to consider when deciding how long you plan to live in a home.


Essentially, this exclusion means that, in many cases, homeowners won’t owe any capital gains tax when they sell their primary residence. It’s a valuable tax benefit that can significantly impact your finances. Keep good records of your purchase price and any capital improvements you make to ensure you can accurately calculate your capital gain and take full advantage of the exclusion when you sell.


Record-Keeping Tips for Homeowners


Organized records are essential for taking advantage of tax deductions and credits. Keep all relevant documents, such as mortgage statements, property tax bills, and receipts for home improvements, readily accessible.15 It’s wise to keep both physical and digital copies (scan and save everything!). Store physical copies securely, perhaps in a safe deposit box. Keep all home-related records for as long as you own the home, plus at least three years after you file your tax returns for the year of the sale.
Conclusion


Homeownership offers numerous opportunities to save on taxes. From mortgage interest and property taxes to energy-efficient upgrades and capital gains exclusions, understanding these deductions and credits can significantly reduce your tax burden. Remember, this information is for general guidance only. Consulting with a qualified tax professional is invaluable for personalized advice.


Have questions about real estate or need a referral to a trusted tax advisor? Contact us today!


Note: This information is intended for general guidance only. Tax regulations are subject to change.


Sources:


  1. IRS –
    https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2025
  2. Nerdwallet –
    https://www.nerdwallet.com/article/taxes/mortgage-interest-rate-deduction
  3. IRS –
    https://www.irs.gov/forms-pubs/about-publication-936
  4. IRS –
    https://www.irs.gov/forms-pubs/about-form-1098
  5. IRS –
    https://www.irs.gov/faqs/itemized-deductions-standard-deduction/real-estate-taxes-mortgage-interest-points-other-property-expenses/real-estate-taxes-mortgage-interest-points-other-property-expenses-5#:~:text=The%20total%20deduction%20allowed%20for,taxes%20or%20sales%20taxes
    )%20is
  6. IRS –
    https://www.irs.gov/taxtopics/tc503#:~:text=Overall%20limit,your%20other%20itemized%20deductions%20also
    .
  7. TurboTax –
    https://turbotax.intuit.com/tax-tips/home-ownership/claiming-property-taxes-on-your-tax-return/L6cSL1QoB
  8. Bankrate –
    https://www.bankrate.com/home-equity/home-equity-loan-tax-changes/#how-to-claim
  9. USNews –
    https://realestate.usnews.com/real-estate/articles/are-home-improvements-tax-deductible
  10. IRS –
    https://www.irs.gov/publications/p523
  11. NOLO –
    https://www.nolo.com/legal-encyclopedia/what-home-improvements-tax-deductible.html
  12. USNews –
    https://money.usnews.com/money/personal-finance/articles/how-consumers-can-save-with-the-new-climate-tax-breaks
  13. IRS –
    https://www.irs.gov/credits-deductions/energy-efficient-home-improvement-credit
  14. Bankrate –
    https://www.bankrate.com/real-estate/capital-gains-tax-on-real-estate/#avoiding-during-home-sale
  15. NOLO –
    https://www.nolo.com/legal-encyclopedia/tax-reasons-keep-good-records-home-improvements.html
October 7, 2026
For most people, moving has come with an assumption built in: you sell the house you're leaving and put the proceeds toward the one you're buying. The only real question is what it will sell for. For more owners this year, that assumption is loosening. The question showing up isn't just "what will it sell for" but "should I sell it at all, or keep it and rent it out?" It's a fair question, and the answer isn't obvious in either direction. Keeping the home can preserve a mortgage rate you'll never see again and turn a house into an income property. It also makes you a landlord, with a tax clock that starts the day it stops being your home and a workload that never shows up on a spreadsheet. Here's how to think it through. Why "Sell or Rent It Out?" Is a Real Question This Year Start with the rate gap. Just over half of homeowners with a mortgage are carrying a rate below 4%,1 while the 30-year fixed has been running around 6.7%.2 Selling means handing that loan back, and the next one costs considerably more for the same money borrowed. The low rate on your current mortgage is an asset, and like any asset, it's worth knowing what it costs you to keep. The market has also loosened. Unsold homes now amount to 4.9 months of supply nationally, the most in more than a decade, and they're taking longer to sell.3 Selling is still a good outcome for plenty of owners, but it's no longer automatic. Rents, meanwhile, have stayed firm in much of the country, so the math on holding a home has gotten more interesting than it was. Put those together and you get a pattern that now has a name. "Accidental landlords," owners who listed a home, didn't get the number they wanted, and rented it out instead, recently reached a three-year high at 2.3% of homes listed for rent.4 As Zillow senior economist Kara Ng put it, "Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price."4 That's a small share of the market, and it's not a wave everyone is riding. But it does tell you the question is live. The smarter move is deciding on purpose, before you list, with the numbers in front of you. Run Both Sets of Numbers, Not Just One Most owners know roughly what their house would sell for and roughly what it might rent for. Those two numbers alone don't answer the question. What matters is what each path nets you, over the years you'd actually hold. On the sell side, that means net proceeds: the sale price minus commission, closing costs, and any repairs or concessions it takes to get the deal done. Then ask what that equity does next. For many owners it becomes the down payment on the next home. For others it pays down higher-rate debt or gets invested. On the rent side, count everything. The mortgage payment is the start. Add property taxes, a maintenance reserve, a vacancy allowance (a month or so a year is a reasonable planning number), and management fees if you won't be handling it yourself. Add the insurance change, too: a standard homeowner's policy doesn't cover a home rented out long-term, and a landlord policy generally costs about 25% more. 5 A rental pays you in three ways, and they arrive at different speeds. Monthly cash flow is often thin, or negative, in the early years. Principal paydown, which the tenant is effectively funding, builds quietly. Appreciation shows up over time. So a house that barely breaks even each month can still be a strong hold if the equity is growing, and a house that cash-flows can still be a poor hold if you need that equity for the next purchase. The comparison that settles it is what your equity earns sitting in the house as a rental versus what it earns deployed somewhere else. Run it with real local numbers for your specific house. Rent, taxes, insurance, and appreciation vary enough from one neighborhood to the next to flip the answer. This is where it pays to bring in someone who does this for a living. A local agent can give you a realistic sale price and a realistic rent for your specific home, based on what comparable homes nearby have actually sold and rented for recently, along with a read on how long each would take. Those two numbers are the foundation everything else in this decision rests on. Get them right first, and the rest of the math gets a lot easier. The Tax Clock Most People Don't Know Is Running The "when" in this decision is largely a tax question. When you sell a home you've lived in, a large portion of the gain can be excluded from capital-gains tax: up to $250,000 for a single filer, or $500,000 for a married couple filing jointly. 6 To qualify, you need to have owned the home and used it as your residence for at least two of the five years ending on the date of sale, and those two years don't have to be consecutive. 6 Renting the home out starts a countdown on that. If you've lived there for the past two years, you can move out today, rent it, and generally go up to about three years before you'd fail the two-of-five test. Rent it longer, and the exclusion narrows or disappears. Renting your home out isn't a permanent decision, but it does have an expiration date on one of its biggest benefits. Depreciation is the other piece. While the home is a rental, you'll deduct a portion of its value each year, which helps every year you hold. Part of that comes back as a tax bill when you sell: the gain equal to the depreciation you took, or were entitled to take, can't be excluded and is taxed separately. 7 That belongs in the plan from the start, not as a surprise at closing. If you find you like being a landlord, there are also ways to sell one rental and buy another without a tax hit at that moment. 8 That's a later conversation, but knowing the option exists changes how "temporary" this decision has to be. This is the section where a good tax professional earns their fee. The point isn't to replace that conversation; it's to make sure you walk into it knowing which questions to ask, and that the calendar is doing part of the math for you. What Actually Changes When You Become a Landlord Turning a home into a rental is a series of practical changes. All of them are manageable, and all of them are better handled before the tenant moves in than after. Your lender. Most primary-residence mortgages require you to move in within 60 days of closing and live there for at least a year. 9 Once that's satisfied, renting is usually fine, but confirm it with your lender, and know that some loan types have their own rules. Your insurance. The switch to a landlord policy is routine, and it isn't optional. Budget for the higher premium. Your HOA, if you have one. Rental caps, minimum lease terms, and approval processes exist in plenty of communities, and they're the reason some owners can't take this path at all. Check before you plan around it. Your tenant. Screening, a proper lease, security deposit rules, and your state's and city's landlord-tenant law. This is the part that goes wrong when it's rushed, and the mistakes are expensive. Your time. Being a landlord is ongoing work with no set hours. Finding and screening tenants, handling repairs and late rent, and the turnover every time someone moves out (cleaning, repairs, re-listing, a vacancy gap) add up to a few hours a month in a quiet stretch and whole days when something breaks or a tenant leaves. The 2 a.m. water heater call is real. Self-managing saves money and costs attention. A property manager takes most of the day-to-day off your plate for a share of the rent, and still leaves you the ownership decisions and the repair bills. Your relationship with the house. It stops being your home. Some owners find that easy and some don't, and it's worth knowing which you are before you've got a lease signed. Nothing on this list is a reason not to do it. All of it is a reason to do it deliberately. When Selling Is the Better Move Keeping the house isn't a free option, and there are plenty of situations where selling is the clearer call. You need equity. If the down payment on the next home depends on this one's proceeds, that usually settles it. Stretching to carry two mortgages is where this decision goes wrong most often. The numbers don't work. Rent that doesn't cover the carrying costs, with no strong case for appreciation, is a monthly subsidy to a house you no longer live in. The house needs work. Deferred maintenance, an aging roof, old systems. Tenants don't defer those costs; they surface them. Your specific home sells well right now. Nationally, the typical home still sold in about a month this summer, 3 and certain price points and neighborhoods are moving faster than that. A softer headline market doesn't mean your house is sitting. You don't want the job, or don't have the hours for it. Being a landlord is ongoing work, not a one-time decision, and not wanting that is a complete reason. Plenty of owners run the numbers, see a decent hold on paper, and still sell because they'd rather have a clean break and a simpler life. Selling into a slower market isn't a loss if the proceeds do something better for you, and holding a house you resent just to protect a rate rarely turns out to be a win. The rate you'd give up is one cost in the decision, not the decision itself. How to Decide, and When to Revisit It Most of this decision comes down to getting five real inputs and looking at them together. 1. Get two real numbers for your home today: what it would sell for, and what it would rent for. Both from someone who knows your local market. 2. Run the two nets over a realistic hold period, counting everything on the rent side. 3. Check the constraints: your lender, your insurance, your HOA, and local rules. 4. Look at the tax window with a professional, and write down the date it closes. 5. Be honest about the job. If the answer to "do I want to be a landlord" is a clear no, the math is secondary. Then build in a review point. Many owners rent for a year or two, reassess against the tax window and the market, and sell or keep with far better information than they had on moving day. Deciding on purpose beats becoming a landlord by default. If you're planning a move and wondering whether to sell your current home or hold onto it, reach out. I can tell you what it would sell for and what it would rent for in today's market, so you're making this decision with real numbers instead of guesses. Sources 1. More Homeowners Have a Rate Above 6% Than a Rate Below 3% For the First Time in 5 Years — Redfin (FHFA National Mortgage Database, Q3 2025; Feb 27, 2026) 2. Mortgage Rates Average 6.71% — Freddie Mac Primary Mortgage Market Survey, Sept 3, 2026 3. NAR Existing-Home Sales Report Shows 2.0% Decrease in August — National Association of REALTORS®, Sept 10, 2026 4. Number of "Accidental Landlords" Rises to Three-Year High — Zillow Research, Mar 11, 2026 5. Coverage for renting out your home — Insurance Information Institute 6. Publication 523 (2025), Selling Your Home — Internal Revenue Service 7. Sales, Trades, Exchanges 3 (sale of a main home also used as a rental) — Internal Revenue Service 8. Like-Kind Exchanges — Real Estate Tax Tips — Internal Revenue Service 9. Fannie Mae/Freddie Mac Uniform Instrument, Single Family Deed of Trust, Covenant 6 "Occupancy" — sample hosted by the Consumer Financial Protection Bureau
September 4, 2026
For most of the internet era, searching for a home meant the same ritual: set your price cap, pick a number of bedrooms, check a few boxes, and scroll. Then the real work started — sifting through pages of results, opening listing after listing, digging for the details that actually mattered. That ritual is quietly starting to give way. Today, a fast-growing share of home searches begin as a conversation: someone typing "find me a home where my mom could live with us, near a park, under our budget" into an AI assistant and getting real answers back. Nearly half of prospective buyers now say they're using AI tools somewhere in the homebuying process.¹ And this isn't happening off in a corner of the tech world. In late 2025, Zillow became the first real estate app built directly into ChatGPT. Actual listings, with photos, maps, and prices, now surface inside the chat itself.² The other major portals have followed with AI search of their own.³ The biggest names in home search have decided the conversation is the new front door. If that sounds like a big shift, it is: roughly the size of the move from newspaper listings to online portals a generation ago. In many ways, it's making the home search easier. But these tools also come with a few things worth watching for. So here's what they're genuinely good at, where they get things wrong, and what the change means whether you're buying or selling. How AI Makes the Home Search Easier Treated as a research assistant, AI is genuinely excellent at the early, wide-open stage of a home search. Start with the search itself. You don't have to translate your life into filter categories anymore; you can describe the life and let the machine translate. "We need space for a home office, my in-laws stay for a month every winter, and I can't do a long commute" is now a workable query. Better still, the conversation continues from there: "more like this one, but with a yard." "What's the tradeoff between these two?" "Which one has the shorter drive to downtown?" The sifting that used to mean twenty open tabs and a lost Saturday? That part, the machine now does. It's also a patient explainer. Escrow, contingencies, HOA rules, points, loan types: you can ask what anything means, at midnight, without feeling like you're asking a dumb question, and keep asking follow-ups until it's actually clear. And it's quick with the math and homework that used to slow everything down. Among buyers using AI, 57% use it to estimate affordability, mortgage payments, or closing costs, and about half use it to research neighborhoods, market trends, or property values.⁴ Rough monthly-cost scenarios that once took a spreadsheet and an afternoon now take minutes, which means you can test more possibilities before committing to any of them. Add it up, and the fog-clearing phase of a home search — figuring out what you actually want, what it costs, and where to look — moves dramatically faster than it did even two years ago. That phase is real work, and this is the stuff AI is genuinely good at. Where AI Gets It Wrong — and How to Catch It AI's failure mode is being confidently wrong : it delivers mistakes in the same fluent, assured tone as facts, and it doesn't flag when it's guessing. Sometimes that means hallucination, the industry's word for AI inventing things: details, listings, even whole answers that sound polished, specific, and true but aren't. Sometimes it just means stale information, like a recommendation built on a home that sold three weeks ago. Then there's a second category, and it matters more: the things AI can't see at all. Condition. It can't see the true condition of the home, or of the competing homes its price comparisons quietly rest on. Feel. It doesn't know how a street actually lives: what it sounds like at rush hour, how it feels on a Saturday morning. School lines. One side of a street can feed a more desirable school, or a standout principal. The map data AI reads won't tell it that. Position. A corner lot and a home tucked deep in the cul-de-sac can carry very different values. AI reads them as the same address. What hasn't been announced. The empty field nearby that's likely to be developed, the rezoning that's still a rumor at the county office: these shape future value, and they live in local knowledge, not datasets. And those are examples, not the whole list. Every neighborhood carries its own intangibles: the plans, reputations, and quirks you only learn by being there, or by talking to someone who has. No portal or chatbot has a column for them. None of this makes AI the wrong tool; it makes verification part of using it well. Treat its answers as leads rather than conclusions, and check anything you'd act on against the live listing, the disclosures, or someone who's actually been inside. You wouldn't make one of the largest financial decisions of your life on a single unverified source in any other context. This is no different. Selling? Your Home's First Showing Is Now to a Machine If you're on the other side of the transaction, the same shift reaches you in a way most sellers haven't considered: before a buyer ever sees your photos, an AI may have already read, summarized, and ranked your listing. When listings surface inside a chat conversation, software is doing the first sort.² Your home either comes up in that conversation or it doesn't, and what decides that is the substance of the listing: the real upgrades, the real layout, the real numbers. Specific, accurate details are what machines can find and repeat. Vague lifestyle copy is what they skip. It also means your photos and your facts need to agree. An AI summary will amplify an inconsistency that a human browser might have skimmed right past. And pricing right matters even more than it used to, because a mispriced home gets quietly filtered out of conversations it never knew were happening. None of this is a crisis — it's a presentation shift. Sellers who understand how homes get found now have a real edge over sellers whose listings are still written for 2019. It's worth asking whoever lists your home how it will read to both audiences: the buyer, and the machine summarizing it for the buyer. What Hasn't Changed (and Won't) AI is at its best in the research phase: gathering, comparing, explaining, estimating. The decisions that determine how the whole thing turns out (what to offer, how to negotiate, when to walk away, how to price) are a different kind of work, and they still come down to judgment. Pricing strategy, offer strategy, and negotiation are calls built on local, current, in-person knowledge. AI can assist the analysis, but it has never walked the block at 6 p.m., smelled the basement, or heard what the neighbors said at the open house. And a home purchase is a life decision wearing a financial costume; a good agent helps you manage both, and a chatbot manages neither. Buyers seem to understand this instinctively. Even as AI use climbs, 88% of buyers still purchased their home through an agent or broker.⁵ And 44% of consumers say they'd pay more for a professional to verify what AI told them.⁶ That instinct is right. An agent's edge is precisely the list of things AI can't see: condition, feel, school lines, lot position, what's about to be built next door. The Smart Way to Run an AI-Assisted Home Search (or Sale) Put it together and it's a simple division of labor. If you're buying: use AI to sharpen your wish list, learn the vocabulary, rough out affordability, and build a candidate list. Then bring that homework to a person who can verify it, tour with you, price it, and negotiate it. If you're selling: ask your agent how your listing reads now, to buyers and to the machines briefing them, and make sure the details and the price can survive both audiences. Either way, what AI actually buys you is speed, clarity, and convenience: answers in minutes instead of weekends, a complicated process explained in plain language, help available whenever you're thinking about it. The numbers already tell the story of how this really works: about half of buyers now start with AI,¹ and 88% still finish with a person.⁵ Let the machine do the homework, and keep a person on the decision. If AI has been part of your home search, or you're wondering how your home would look through its eyes, reach out. Bring me what the chatbot told you, and I'll tell you what it got right. Sources  1. 2026 Home Buyer Report — NerdWallet (The Harris Poll, Nov 2025) 2. Zillow becomes the only real estate app in ChatGPT — Zillow, Oct 6, 2025 3. Realtor.com the latest portal to launch search app in ChatGPT — Real Estate News, Mar 30, 2026 4. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Bank of America Homebuyer Insights Report) 5. 2025 Profile of Home Buyers and Sellers — National Association of REALTORS® 6. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Cotality consumer survey)
August 5, 2026
For the past two years, a lot of people have been waiting on the housing market to do one specific thing: drop rates dramatically and "unfreeze." That was the plan for buyers and sellers alike. I'll move when rates come down. That big drop never fully arrived. And the market changed anyway. It didn't unfreeze. It thawed — slowly. Halfway through 2026, buyers in many markets have more homes to choose from, more time to decide, and more room to negotiate than they've had in years. Sellers are adjusting to a slower, more selective market. It's not a perfectly balanced market everywhere. But compared to the pandemic-era bidding wars, and the frozen, locked-up market that followed them, it looks a lot more balanced. Nobody rings a bell when a market becomes more negotiable. Booms and crashes make headlines; a market quietly returning to normal doesn't. So consider this your mid-year bell: here's what the first half of 2026 actually tells us, and what it means whether you're buying, selling, or staying put. More Homes, More Time, More Conversation Start with what changed. There are meaningfully more homes on the market than during the low-inventory years: about 1.56 million listings nationally as of June, or 4.6 months of supply.¹ That's not a glut, and the growth has been leveling off as some would-be sellers step back rather than chase the market. But for buyers who spent years picking from slim inventory, it's a real difference. And the market isn't frozen. Sales bounce around from month to month, but they're running ahead of where they were a year ago.¹ People are moving without the dramatic rate drop everyone was waiting on. The bigger shift is in how deals come together. Negotiation is a standard part of the process again. Nearly half of sellers, 46% in May, gave buyers some form of concession, a record for that month.² Price reductions are far more common than they were during the frenzy. For buyers, that's a signal of how negotiable this market is, not necessarily a problem with the home. Inspections, repairs, closing costs, timing: these are conversations again, not sacrifices you make to win a bidding war. More negotiation doesn't mean buyers control every market. A well-priced home in a tight area can still sell fast, sometimes with competition. What it means for you: if you're buying, the list price is no longer the whole conversation. A reduced price is often an invitation to look closer, not a reason to stay away. If you're selling, the lesson runs the other way: strategy matters more than optimism. The goal is to price right on day one so you never need the cut. Homes that reduce are usually correcting a pricing decision the market already voted on. Rates Are No Longer the Only Story Mortgage rates spent the first half of the year drifting rather than diving. The average 30-year fixed rate was 6.49% in mid-July, a shade better than the 6.72% from a year ago, but nowhere near the dramatic relief people were holding out for.³ The market improved anyway. Affordability has quietly been getting better. Buying power stretches a little further than it did a year ago, as income growth outpaces home-price growth in most of the country.¹ Not dramatically. Cumulatively. And the people transacting in 2026 aren't necessarily the ones who timed the market perfectly. They're the ones whose lives changed: a new job, a growing family, a downsize, a divorce, a retirement, a relocation. Life decisions, not rate decisions, are driving moves again. Waiting has a cost too. I've watched plenty of buyers hold out for a rate that never arrived while their needs kept changing, like the family that outgrew their space two years ago, or the retiree maintaining a house that stopped making sense. If the only thing keeping you on the sidelines is a number, it's worth running the math on what waiting is actually costing you. What it means for you: rates still shape affordability, but they're not the whole plot anymore. Price, concessions, inspection terms, timing, and the right property all shape the outcome too. You can't control the rate — you can control almost everything you negotiate around it. What the National Numbers Can Miss The national market barely exists. Conditions differ sharply by region, price point, and property type. Some markets have tipped genuinely toward buyers, with more listings, longer timelines, and real leverage. Others remain stubbornly tight, with limited supply and quick sales. Even price direction is diverging: some regions are still posting solid annual gains while others have flattened out.¹ Two buyers with similar budgets can have completely opposite experiences depending on where and what they're shopping for. The national median price tells the same story in one number: $440,600 in June, up just 1.8% from a year ago.¹ A modest gain, but that one number is an average of markets moving in different directions. This is exactly where the gap between the headline and your street gets expensive. What it means for you: national headlines tell you the direction of the market. They can't tell you what your home is worth, what your competition looks like, or how much negotiating room exists in your neighborhood. Only a local read can. What It Means for You — Buyers, Sellers, and the Staying-Put A more balanced, more local market rewards preparation over timing. What that looks like depends on whether you're buying, selling, or staying put. If you're buying: you have more choice and, in many markets, more leverage than you've had in years. Use the time this market gives you: inspect thoroughly, negotiate genuinely, and compare concessions, not just list prices. A seller-paid rate buydown or closing-cost credit can sometimes do more for your monthly payment than a modest price cut. First-time buyers are finding more entry points than they have in years, making up 33% of June's buyers¹, but affordability still requires discipline. More options doesn't mean easy. If you're selling: you can absolutely still win in this market. But pricing right from day one, presenting well, and expecting negotiation are now the job description. "Testing the market" with an ambitious price costs real time and real money. The homes that sit are usually the ones that priced for 2021. If you're staying put: a calmer market is a good moment for a low-stakes check-in. What's your home worth now? What does your equity look like? Does this home still fit your life? No urgency, just awareness. The forecast for the second half of the year calls for modestly better sales, not fireworks⁴, which means this planning window stays open. Across all three: the second half of the year favors people who know their local numbers, not people waiting for a national signal. Balance doesn't pick winners. Preparation does. The Second Half Belongs to the Prepared That's the mid-year picture: more choice, steadier rates, more negotiation, and conditions that are sharply local. For the first time in a while, this is a market you can plan in rather than react to. The national story is the easy part — you just read it. The part you can't Google is what it means on your street, for your home, on your timeline. If you're wondering what this market means for your specific situation, reach out. Whether you're thinking about buying, selling, or just want to know where your home stands, that's exactly the kind of conversation I'm happy to have, no pressure attached. Sources 1. Existing-Home Sales Report, June 2026 — National Association of REALTORS® 2. 46% of Home Sellers Gave Concessions to Buyers in May — Redfin 3. Primary Mortgage Market Survey, July 9, 2026 — Freddie Mac 4. NAR Chief Economist Lawrence Yun: Home Sales Expected to Improve in Second Half of 2026 — National Association of REALTORS®