September 7, 2022

8 Strategies to Secure a Lower Mortgage Rate

Mortgage rates have been on a roller coaster ride this year, rising and falling amid inflationary pressures and economic uncertainty. And even the experts are divided when it comes to predicting where rates are headed next.1


This climate has been unsettling for some homebuyers and sellers. However, with proper planning, you can work toward qualifying for the best mortgage rates available today – and open up the possibility of refinancing at a lower rate in the future.

How does a lower mortgage rate save you money? According to Trading Economics, the average new mortgage size in the United States is currently around $410,000.2 Let’s compare a 5.0% versus a 6.0% fixed-interest rate on that amount over a 30-year term.
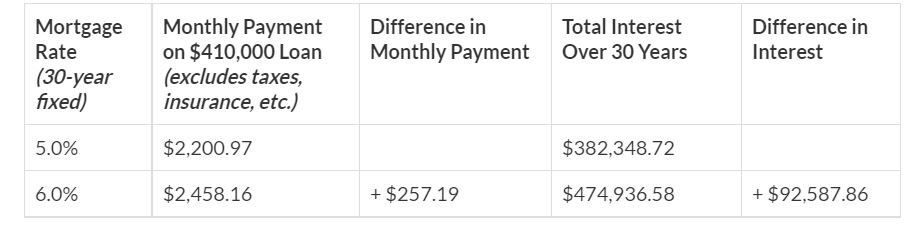
With a 5% rate, your monthly payments would be about $2,201. At 6%, those payments would jump to $2,458, or around $257 more. That adds up to a difference of almost $92,600 over the lifetime of the loan. In other words, shaving off just one percentage point on your mortgage could put nearly $100K in your pocket over time.

So, how can you improve your chances of securing a low mortgage rate? Try these eight strategies:


Raise your credit score.

Borrowers with higher credit scores are viewed as “less risky” to lenders, so they are offered lower interest rates. A good credit score typically starts at 690 and can move up into the 800s.3 If you don’t know your score, check with your bank or credit card company to see if they offer free access. If not, there are a plethora of both free and paid credit monitoring services you can utilize.

If your credit score is low, you can take steps to improve it, including:4

  • Correct any errors on your credit reports, which can bring down your score. You can access reports for free by visiting AnnualCreditReport.com.
  • Pay down revolving debt. This includes credit card balances and home equity lines of credit.
  • Avoid closing old credit card accounts in good standing. It could lower your score by shortening your credit history and shrinking your total available credit.
  • Make all future payments on time. Payment history is a primary factor in determining your credit score, so make it a priority.
  • Limit your credit applications to avoid having your score dinged by too many inquiries. If you’re shopping around for a car loan or mortgage, minimize the impact by limiting your applications to a short period, usually 14 to 45 days.5

Over time, you should start to see your credit score climb — which will help you qualify for a lower mortgage rate.


Keep steady employment.

If you are preparing to purchase a home, it might not be the best time to make a major career change. Unfortunately, frequent job moves or gaps in your résumé could hurt your borrower eligibility.

When you apply for a mortgage, lenders will typically review your employment and income over the past 24 months.5 If you’ve earned a steady paycheck, you could qualify for a better interest rate. A stable employment history gives lenders more confidence in your ability to repay the loan.

That doesn’t mean a job change will automatically disqualify you from purchasing a home. But certain moves, like switching from W-2 to 1099 (independent contractor) income, could throw a wrench in your home buying plans.6


Lower your debt-to-income ratios.

Even with a high credit score and a great job, lenders will be concerned if your debt payments are consuming too much of your income. That’s where your debt-to-income (DTI) ratios will come into play.

There are two types of DTI ratios:7

  1. Front-end ratio — What percentage of your gross monthly income will go towards covering housing expenses (mortgage, taxes, insurance, and dues or association fees)?
  2. Back-end ratio — What percentage of your gross monthly income will go towards covering ALL debt obligations (housing expenses, credit cards, student loans, and other debt)?

What’s considered a good DTI ratio? For better rates, lenders typically want to see a front-end DTI ratio that’s no higher than 28% and a back-end ratio that’s 36% or less.7

If your DTI ratios are higher, you can take steps to lower them, like purchasing a less expensive home or increasing your down payment. Your back-end ratio can also be decreased by paying down your existing debt. A bump in your monthly income will also bring down your DTI ratios.


Increase your down payment.

Minimum down payment requirements vary by loan type. But, in some cases, you can qualify for a lower mortgage rate if you make a larger down payment.8

Why do lenders care about your down payment size? Because borrowers with significant equity in their homes are less likely to default on their mortgages. That’s why conventional lenders often require borrowers to purchase private mortgage insurance (PMI) if they put down less than 20%.

A larger down payment will also lower your overall borrowing costs and decrease your monthly mortgage payment since you’ll be taking out a smaller loan. Just be sure to keep enough cash on hand to cover closing costs, moving expenses, and any furniture or other items you’ll need to get settled into your new space.


Compare loan types.

All mortgages are not created equal. The loan type you choose could save (or cost) you money depending on your qualifications and circumstances.

For example, here are several common loan types available in the U.S. today:9

  • Conventional — These offer lower mortgage rates but have more stringent credit and down payment requirements than some other types.
  • FHA — Backed by the government, these loans are easier to qualify for but often charge a higher interest rate.
  • Specialty — Certain specialty loans, like VA or USDA loans, might be available if you meet specific criteria.
  • Jumbo — Mortgages that exceed the local conforming loan limit are subject to stricter requirements and may have higher interest rates and fees.10

When considering loan type, you’ll also want to weigh the pros and cons of a fixed-rate versus variable-rate mortgage:11

  • Fixed rate — With a fixed-rate mortgage, you’re guaranteed to keep the same interest rate for the entire life of the loan. Traditionally, these have been the most popular type of mortgage in the U.S. because they offer stability and predictability.
  • Adjustable rate — Adjustable-rate mortgages, or ARMs, have a lower introductory interest rate than fixed-rate mortgages, but the rate can rise after a set period of time — typically 3 to 10 years.

According to the Mortgage Bankers Association, 10% of American homebuyers are now selecting ARMs, up from just 4% at the start of this year.12 An ARM might be a good option if you plan to sell your home before the rate resets. However, life is unpredictable, so it’s important to weigh the benefits and risks involved.


Shorten your mortgage term.

A mortgage term is the length of time your mortgage agreement is in effect. The terms are typically 15, 20, or 30 years.13 Although the majority of homebuyers choose 30-year terms, if your goal is to minimize the amount you pay in interest, you should crunch the numbers on a 15-year or 20-year mortgage.

With shorter loan terms, the risk of default is less, so lenders typically offer lower interest rates.13 However, it’s important to note that even though you’ll pay less interest, your mortgage payment will be higher each month, since you’ll be making fewer total payments. So before you agree to a shorter term, make sure you have enough room in your budget to comfortably afford the larger payment.

 
Get quotes from multiple lenders.

When shopping for a mortgage, be sure to solicit quotes from several different lenders and lender types to compare the interest rates and fees. Depending upon your situation, you could find that one institution offers a better deal for the type of loan and term length you want.

Some borrowers choose to work with a mortgage broker. Like an insurance broker, they can help you gather quotes and find the best rate. However, if you use a broker, make sure you understand how they are compensated and contact more than one so you can compare their recommendations and fees.14

Don’t forget that we can be a valuable resource in finding a lender, especially if you are new to the home buying process. After a consultation, we can discuss your financing needs and connect you with loan officers or brokers best suited for your situation.


Consider mortgage points.

Even if you score a great interest rate on your mortgage, you can lower it even further by paying for points. When you buy mortgage points — also known as discount points — you essentially pay your lender an upfront fee in exchange for a lower interest rate. The cost to purchase a point is 1% of your mortgage amount. For each point you buy, your mortgage rate will decrease by a set amount, typically 0.25%.15 You’ll need upfront cash to pay for the points, but you can more than makeup for the cost in interest savings over time.

However, it only makes sense to buy mortgage points if you plan to stay in the home long enough to recoup the cost. You can determine the breakeven point or the period of time you’d need to keep the mortgage to make up for the fee, by dividing the cost by the amount saved each month.15 This can help you determine whether or not mortgage points would be a good investment for you.


Getting Started

Unfortunately, the rock-bottom mortgage rates we saw during the height of the pandemic are behind us. However, today’s 30-year fixed rates still fall beneath the historical average of around 8% — and are well below the all-time peak of 18.45% in 1981.16, 17

And although higher mortgage rates have made it more expensive to finance a home purchase, they have also eliminated some of the competition from the market. Consequently, today’s buyers are finding more homes to choose from, fewer bidding wars, and more sellers willing to negotiate or offer incentives such as cash toward closing costs or mortgage points.

If you’re ready and able to buy a home, there’s no reason that concerns about mortgage rates should sideline your plans. The reality is that many economists predict home prices to continue climbing.18 So you may be better off buying today at a slightly higher rate than waiting and paying more for a home a few years from now. You can always refinance if mortgage rates go down, but you can’t make up for the lost years of equity growth and appreciation.


If you have questions or would like more information about buying or selling a home, reach out to schedule a free consultation. We’d love to help you weigh your options, navigate this shifting market, and reach your real estate goals!


Sources:

  1. Washington Post –
    https://www.washingtonpost.com/business/2022/08/04/mortgage-rates-sink-below-5-percent-first-time-four-months/
  2. Trading Economics –
    https://tradingeconomics.com/united-states/average-mortgage-size
  3. NerdWallet –
    https://www.nerdwallet.com/article/finance/what-is-a-good-credit-score
  4. Debt.org –
    https://www.debt.org/credit/improving-your-score/
  5. The Balance –
    https://www.thebalance.com/will-multiple-loan-applications-hurt-my-credit-score-960544
  6. Time –
    https://time.com/nextadvisor/mortgages/how-lenders-evaluate-your-employment/
  7. Bankrate –
    https://www.bankrate.com/mortgages/why-debt-to-income-matters-in-mortgages/
  8. NerdWallet –
    https://www.nerdwallet.com/article/mortgages/payment-buy-home
  9. Consumer Financial Protection Bureau –
    https://www.consumerfinance.gov/owning-a-home/loan-options/
  10. NerdWallet –
    https://www.nerdwallet.com/article/mortgages/jumbo-loans-what-you-need-to-know
  11. Bankrate –
    https://www.bankrate.com/mortgages/arm-vs-fixed-rate/
  12. MarketWatch –
    https://www.marketwatch.com/picks/as-mortgage-rates-rise-heres-exactly-how-more-homebuyers-are-snagging-mortgage-rates-around-4-01656513665
  13. Consumer Financial Protection Bureau –
    https://www.consumerfinance.gov/owning-a-home/loan-options/#anchor_loan-term_361c08846349fe
  14. Federal Trade Commission –
    https://consumer.ftc.gov/articles/shopping-mortgage-faqs
  15. Bankrate –
    https://www.bankrate.com/mortgages/mortgage-points/
  16. CNBC –
    https://www.cnbc.com/select/mortgage-rates-today-still-relatively-low/
  17. Rocket Mortgage –
    https://www.rocketmortgage.com/learn/historical-mortgage-rates-30-year-fixed
  18. MarketWatch –
    https://www.marketwatch.com/picks/continuing-home-price-deceleration-heres-what-5-economists-and-real-estate-pros-predict-will-happen-to-the-housing-market-this-year-01659347993
September 4, 2026
For most of the internet era, searching for a home meant the same ritual: set your price cap, pick a number of bedrooms, check a few boxes, and scroll. Then the real work started — sifting through pages of results, opening listing after listing, digging for the details that actually mattered. That ritual is quietly starting to give way. Today, a fast-growing share of home searches begin as a conversation: someone typing "find me a home where my mom could live with us, near a park, under our budget" into an AI assistant and getting real answers back. Nearly half of prospective buyers now say they're using AI tools somewhere in the homebuying process.¹ And this isn't happening off in a corner of the tech world. In late 2025, Zillow became the first real estate app built directly into ChatGPT. Actual listings, with photos, maps, and prices, now surface inside the chat itself.² The other major portals have followed with AI search of their own.³ The biggest names in home search have decided the conversation is the new front door. If that sounds like a big shift, it is: roughly the size of the move from newspaper listings to online portals a generation ago. In many ways, it's making the home search easier. But these tools also come with a few things worth watching for. So here's what they're genuinely good at, where they get things wrong, and what the change means whether you're buying or selling. How AI Makes the Home Search Easier Treated as a research assistant, AI is genuinely excellent at the early, wide-open stage of a home search. Start with the search itself. You don't have to translate your life into filter categories anymore; you can describe the life and let the machine translate. "We need space for a home office, my in-laws stay for a month every winter, and I can't do a long commute" is now a workable query. Better still, the conversation continues from there: "more like this one, but with a yard." "What's the tradeoff between these two?" "Which one has the shorter drive to downtown?" The sifting that used to mean twenty open tabs and a lost Saturday? That part, the machine now does. It's also a patient explainer. Escrow, contingencies, HOA rules, points, loan types: you can ask what anything means, at midnight, without feeling like you're asking a dumb question, and keep asking follow-ups until it's actually clear. And it's quick with the math and homework that used to slow everything down. Among buyers using AI, 57% use it to estimate affordability, mortgage payments, or closing costs, and about half use it to research neighborhoods, market trends, or property values.⁴ Rough monthly-cost scenarios that once took a spreadsheet and an afternoon now take minutes, which means you can test more possibilities before committing to any of them. Add it up, and the fog-clearing phase of a home search — figuring out what you actually want, what it costs, and where to look — moves dramatically faster than it did even two years ago. That phase is real work, and this is the stuff AI is genuinely good at. Where AI Gets It Wrong — and How to Catch It AI's failure mode is being confidently wrong : it delivers mistakes in the same fluent, assured tone as facts, and it doesn't flag when it's guessing. Sometimes that means hallucination, the industry's word for AI inventing things: details, listings, even whole answers that sound polished, specific, and true but aren't. Sometimes it just means stale information, like a recommendation built on a home that sold three weeks ago. Then there's a second category, and it matters more: the things AI can't see at all. Condition. It can't see the true condition of the home, or of the competing homes its price comparisons quietly rest on. Feel. It doesn't know how a street actually lives: what it sounds like at rush hour, how it feels on a Saturday morning. School lines. One side of a street can feed a more desirable school, or a standout principal. The map data AI reads won't tell it that. Position. A corner lot and a home tucked deep in the cul-de-sac can carry very different values. AI reads them as the same address. What hasn't been announced. The empty field nearby that's likely to be developed, the rezoning that's still a rumor at the county office: these shape future value, and they live in local knowledge, not datasets. And those are examples, not the whole list. Every neighborhood carries its own intangibles: the plans, reputations, and quirks you only learn by being there, or by talking to someone who has. No portal or chatbot has a column for them. None of this makes AI the wrong tool; it makes verification part of using it well. Treat its answers as leads rather than conclusions, and check anything you'd act on against the live listing, the disclosures, or someone who's actually been inside. You wouldn't make one of the largest financial decisions of your life on a single unverified source in any other context. This is no different. Selling? Your Home's First Showing Is Now to a Machine If you're on the other side of the transaction, the same shift reaches you in a way most sellers haven't considered: before a buyer ever sees your photos, an AI may have already read, summarized, and ranked your listing. When listings surface inside a chat conversation, software is doing the first sort.² Your home either comes up in that conversation or it doesn't, and what decides that is the substance of the listing: the real upgrades, the real layout, the real numbers. Specific, accurate details are what machines can find and repeat. Vague lifestyle copy is what they skip. It also means your photos and your facts need to agree. An AI summary will amplify an inconsistency that a human browser might have skimmed right past. And pricing right matters even more than it used to, because a mispriced home gets quietly filtered out of conversations it never knew were happening. None of this is a crisis — it's a presentation shift. Sellers who understand how homes get found now have a real edge over sellers whose listings are still written for 2019. It's worth asking whoever lists your home how it will read to both audiences: the buyer, and the machine summarizing it for the buyer. What Hasn't Changed (and Won't) AI is at its best in the research phase: gathering, comparing, explaining, estimating. The decisions that determine how the whole thing turns out (what to offer, how to negotiate, when to walk away, how to price) are a different kind of work, and they still come down to judgment. Pricing strategy, offer strategy, and negotiation are calls built on local, current, in-person knowledge. AI can assist the analysis, but it has never walked the block at 6 p.m., smelled the basement, or heard what the neighbors said at the open house. And a home purchase is a life decision wearing a financial costume; a good agent helps you manage both, and a chatbot manages neither. Buyers seem to understand this instinctively. Even as AI use climbs, 88% of buyers still purchased their home through an agent or broker.⁵ And 44% of consumers say they'd pay more for a professional to verify what AI told them.⁶ That instinct is right. An agent's edge is precisely the list of things AI can't see: condition, feel, school lines, lot position, what's about to be built next door. The Smart Way to Run an AI-Assisted Home Search (or Sale) Put it together and it's a simple division of labor. If you're buying: use AI to sharpen your wish list, learn the vocabulary, rough out affordability, and build a candidate list. Then bring that homework to a person who can verify it, tour with you, price it, and negotiate it. If you're selling: ask your agent how your listing reads now, to buyers and to the machines briefing them, and make sure the details and the price can survive both audiences. Either way, what AI actually buys you is speed, clarity, and convenience: answers in minutes instead of weekends, a complicated process explained in plain language, help available whenever you're thinking about it. The numbers already tell the story of how this really works: about half of buyers now start with AI,¹ and 88% still finish with a person.⁵ Let the machine do the homework, and keep a person on the decision. If AI has been part of your home search, or you're wondering how your home would look through its eyes, reach out. Bring me what the chatbot told you, and I'll tell you what it got right. Sources  1. 2026 Home Buyer Report — NerdWallet (The Harris Poll, Nov 2025) 2. Zillow becomes the only real estate app in ChatGPT — Zillow, Oct 6, 2025 3. Realtor.com the latest portal to launch search app in ChatGPT — Real Estate News, Mar 30, 2026 4. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Bank of America Homebuyer Insights Report) 5. 2025 Profile of Home Buyers and Sellers — National Association of REALTORS® 6. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Cotality consumer survey)
August 5, 2026
For the past two years, a lot of people have been waiting on the housing market to do one specific thing: drop rates dramatically and "unfreeze." That was the plan for buyers and sellers alike. I'll move when rates come down. That big drop never fully arrived. And the market changed anyway. It didn't unfreeze. It thawed — slowly. Halfway through 2026, buyers in many markets have more homes to choose from, more time to decide, and more room to negotiate than they've had in years. Sellers are adjusting to a slower, more selective market. It's not a perfectly balanced market everywhere. But compared to the pandemic-era bidding wars, and the frozen, locked-up market that followed them, it looks a lot more balanced. Nobody rings a bell when a market becomes more negotiable. Booms and crashes make headlines; a market quietly returning to normal doesn't. So consider this your mid-year bell: here's what the first half of 2026 actually tells us, and what it means whether you're buying, selling, or staying put. More Homes, More Time, More Conversation Start with what changed. There are meaningfully more homes on the market than during the low-inventory years: about 1.56 million listings nationally as of June, or 4.6 months of supply.¹ That's not a glut, and the growth has been leveling off as some would-be sellers step back rather than chase the market. But for buyers who spent years picking from slim inventory, it's a real difference. And the market isn't frozen. Sales bounce around from month to month, but they're running ahead of where they were a year ago.¹ People are moving without the dramatic rate drop everyone was waiting on. The bigger shift is in how deals come together. Negotiation is a standard part of the process again. Nearly half of sellers, 46% in May, gave buyers some form of concession, a record for that month.² Price reductions are far more common than they were during the frenzy. For buyers, that's a signal of how negotiable this market is, not necessarily a problem with the home. Inspections, repairs, closing costs, timing: these are conversations again, not sacrifices you make to win a bidding war. More negotiation doesn't mean buyers control every market. A well-priced home in a tight area can still sell fast, sometimes with competition. What it means for you: if you're buying, the list price is no longer the whole conversation. A reduced price is often an invitation to look closer, not a reason to stay away. If you're selling, the lesson runs the other way: strategy matters more than optimism. The goal is to price right on day one so you never need the cut. Homes that reduce are usually correcting a pricing decision the market already voted on. Rates Are No Longer the Only Story Mortgage rates spent the first half of the year drifting rather than diving. The average 30-year fixed rate was 6.49% in mid-July, a shade better than the 6.72% from a year ago, but nowhere near the dramatic relief people were holding out for.³ The market improved anyway. Affordability has quietly been getting better. Buying power stretches a little further than it did a year ago, as income growth outpaces home-price growth in most of the country.¹ Not dramatically. Cumulatively. And the people transacting in 2026 aren't necessarily the ones who timed the market perfectly. They're the ones whose lives changed: a new job, a growing family, a downsize, a divorce, a retirement, a relocation. Life decisions, not rate decisions, are driving moves again. Waiting has a cost too. I've watched plenty of buyers hold out for a rate that never arrived while their needs kept changing, like the family that outgrew their space two years ago, or the retiree maintaining a house that stopped making sense. If the only thing keeping you on the sidelines is a number, it's worth running the math on what waiting is actually costing you. What it means for you: rates still shape affordability, but they're not the whole plot anymore. Price, concessions, inspection terms, timing, and the right property all shape the outcome too. You can't control the rate — you can control almost everything you negotiate around it. What the National Numbers Can Miss The national market barely exists. Conditions differ sharply by region, price point, and property type. Some markets have tipped genuinely toward buyers, with more listings, longer timelines, and real leverage. Others remain stubbornly tight, with limited supply and quick sales. Even price direction is diverging: some regions are still posting solid annual gains while others have flattened out.¹ Two buyers with similar budgets can have completely opposite experiences depending on where and what they're shopping for. The national median price tells the same story in one number: $440,600 in June, up just 1.8% from a year ago.¹ A modest gain, but that one number is an average of markets moving in different directions. This is exactly where the gap between the headline and your street gets expensive. What it means for you: national headlines tell you the direction of the market. They can't tell you what your home is worth, what your competition looks like, or how much negotiating room exists in your neighborhood. Only a local read can. What It Means for You — Buyers, Sellers, and the Staying-Put A more balanced, more local market rewards preparation over timing. What that looks like depends on whether you're buying, selling, or staying put. If you're buying: you have more choice and, in many markets, more leverage than you've had in years. Use the time this market gives you: inspect thoroughly, negotiate genuinely, and compare concessions, not just list prices. A seller-paid rate buydown or closing-cost credit can sometimes do more for your monthly payment than a modest price cut. First-time buyers are finding more entry points than they have in years, making up 33% of June's buyers¹, but affordability still requires discipline. More options doesn't mean easy. If you're selling: you can absolutely still win in this market. But pricing right from day one, presenting well, and expecting negotiation are now the job description. "Testing the market" with an ambitious price costs real time and real money. The homes that sit are usually the ones that priced for 2021. If you're staying put: a calmer market is a good moment for a low-stakes check-in. What's your home worth now? What does your equity look like? Does this home still fit your life? No urgency, just awareness. The forecast for the second half of the year calls for modestly better sales, not fireworks⁴, which means this planning window stays open. Across all three: the second half of the year favors people who know their local numbers, not people waiting for a national signal. Balance doesn't pick winners. Preparation does. The Second Half Belongs to the Prepared That's the mid-year picture: more choice, steadier rates, more negotiation, and conditions that are sharply local. For the first time in a while, this is a market you can plan in rather than react to. The national story is the easy part — you just read it. The part you can't Google is what it means on your street, for your home, on your timeline. If you're wondering what this market means for your specific situation, reach out. Whether you're thinking about buying, selling, or just want to know where your home stands, that's exactly the kind of conversation I'm happy to have, no pressure attached. Sources 1. Existing-Home Sales Report, June 2026 — National Association of REALTORS® 2. 46% of Home Sellers Gave Concessions to Buyers in May — Redfin 3. Primary Mortgage Market Survey, July 9, 2026 — Freddie Mac 4. NAR Chief Economist Lawrence Yun: Home Sales Expected to Improve in Second Half of 2026 — National Association of REALTORS®
July 1, 2026
When most people picture negotiating on a home, they picture one number: the list price. You offer somewhere under the asking price, the seller counters, you settle in the middle, and whoever gives up the most ground "loses." For a lot of buyers, that back-and-forth over the sale price is the negotiation. It's only a fraction of it. The price is the headline. The real negotiation happens in the terms underneath it, and right now those terms are where the money is. Buyers have more room to ask than they've had in years. The market has tilted in their favor, and it's showing up at the closing table: in 2025, 62.2% of buyers paid below the list price, and the typical below-list buyer saved 7.9% — about $31,592 — the biggest discount in over a decade.¹ So here's what actually separates the buyers who come out ahead. It isn't the ones who push hardest on the price. It's the ones who understand everything that's on the table, and know which things are worth asking for. The Price-Only Trap It's easy to assume a seller cares about one thing: the highest possible number. In practice, most care about more than that. They care about certainty, meaning whether the deal will actually close. They care about timing. They care about whether your financing will hold together or fall apart three weeks in. That matters for you, because it means you have more to work with than a single figure. A buyer who treats the offer as a package — price, terms, timing, and risk all together — can often create a better outcome than a buyer who just hammers on price and calls it a day. That's why a clean, well-structured offer can beat a higher one: to the right seller, the certainty is worth more than the extra dollars. So before you anchor on a number, widen the lens. Here's what else is on the table. The Money Levers Beyond the Price Some of the most valuable things you can ask for never touch the sale price at all. They change what you actually pay out of pocket. Start with a seller concession. This is money the seller agrees to credit you at closing, most often to cover part of your closing costs, which typically run 2% to 5% of the purchase price.² Rather than cutting the sale price, the seller puts cash toward those costs, lowering what you need to bring on closing day. It's worth asking for any time your upfront cash is the tightest constraint, which for a lot of buyers it is. And it's far from a long shot right now: about 44% of sellers recently gave buyers a concession of some kind, close to the highest share on record.³ A rate buydown is one of the least understood levers, and one of the most valuable. When you buy down the rate, someone pays the lender an upfront sum in exchange for a lower mortgage interest rate. In a negotiation, you ask the seller to be the one who pays it. A buydown can be permanent, lowering your rate for the life of the loan, or temporary. A common version, the "2-1 buydown," cuts two percentage points off your rate the first year and one point the second, then settles at the full rate. Builders have leaned on this hard: 64% were offering incentives like buydowns and closing-cost help earlier this year.⁴ It's worth understanding why this can beat a price cut outright. Take $10,000 off the sale price and your monthly payment barely moves, maybe a few dollars on a 30-year loan. Put that same $10,000 toward buying down your rate, and you feel it in every payment for as long as you own the home. It's the same money out of the seller's pocket, but a far bigger result in yours. The Inspection Is Your Second Negotiation Most buyers treat the home inspection as a hurdle to clear: pass it, and you move on. It's better understood as a second negotiation, and the leverage is usually built in, because an inspection on almost any home turns up something worth addressing. When it does, you generally have two options. You can ask the seller to make the repairs before closing, or ask for a credit instead so you can handle the work yourself afterward. The credit is often the cleaner win. You control the contractor, the timeline, and the quality of the work, instead of depending on a seller's rushed, last-minute fix. A few rules of thumb. Focus on what genuinely matters, meaning health, safety, and the big-ticket systems like the roof, HVAC, or foundation, rather than nickel-and-diming every cosmetic flaw. Consider asking for a home warranty to cover the things that tend to break after you move in. And treat the report as a planning tool, not just a bargaining chip. A fifteen-year-old water heater isn't a reason to walk away. It's a heads-up that helps you budget. Terms and Timeline: The Wins That Aren't About Money One of the most powerful levers costs you nothing: flexibility. To a seller, time is often worth as much as dollars. Say the sellers need a few extra weeks in the home because their next place isn't ready. Offering a rent-back, which lets them stay on for a short period after closing, can make your offer the one they choose even over a higher bid. Or maybe they need to close fast, and you're in a position to deliver. The closing date, the possession date, the length of your contingency periods, even how your earnest money is structured: all of it is something you can shape. The strategic move is simple. Give the seller the timeline they need, and you'll often get the terms you want in return. What Actually Comes With the House This is the simplest ask of all, and the one buyers most often forget to make: what physically stays with the house. Appliances, window treatments, the mounted TVs, the washer and dryer, sometimes even furniture or the patio set you admired during the showing. A lot of it is negotiable. The law draws a line between fixtures, which are generally included, and personal property, which generally isn't, and that line is exactly where a quick ask can pay off. One rule matters above the rest: get every extra written into the contract. A friendly "sure, we'll leave the fridge" during a showing means nothing if it isn't on paper. And if there's something you want, ask for it. The worst answer you'll get is no. How to Actually Use the Whole Menu Knowing what's negotiable is the easy part. Using it well is what turns a list of asks into a better deal. The buyers who succeed don't fire off every possible demand at once. They lead with what the seller values most, group their requests thoughtfully, and avoid the death-by-a-thousand-cuts approach that makes a seller dig in. Above all, they read the seller's real motivation, and that's where a skilled agent earns their keep. It's no accident that 88% of buyers work with an agent, and that the help they value most is negotiating the terms of the deal.⁵ A calm, well-prepared buyer with a clear strategy almost always does better than an aggressive one throwing elbows. The goal isn't to beat the seller. It's to structure a deal that works for both sides, and to make sure you're not leaving value on the table you never knew was there. If you're getting ready to buy, this is exactly the kind of thing worth talking through before you write an offer. I'm glad to walk through everything you could be asking for in your particular situation. No pressure, just a clear picture so you can make a confident decision. Sources Redfin — Homebuyers Are Scoring the Biggest Discounts in 13 Years Redfin — What Are Closing Costs and How Much Will You Pay? Redfin — 44% of Home Sellers Are Giving Concessions to Buyers NAHB / WTOP — Builder Incentives and Rate Buydowns NAR — 2025 Profile of Home Buyers and Sellers