April 4, 2025

5 ROADBLOCKS TO AFFORDABLE HOMEOWNERSHIP (AND WAYS TO MOVE PAST THEM)

Dreaming of a new home but feeling priced out? You’re not alone! According to a recent survey by Bankrate, 78% of aspiring homebuyers cite affordability issues as their primary deterrent.1


According to data from the U.S. Census Bureau, home prices have risen around 32% since the pandemic, and elevated mortgage rates have caused monthly payments to balloon.2
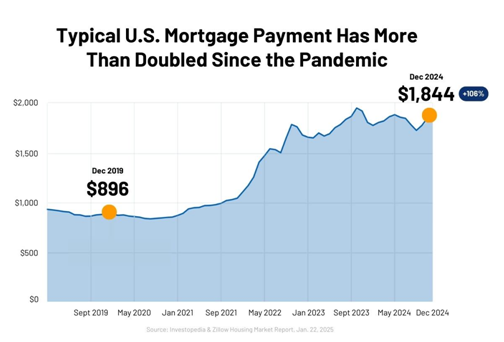
Despite the challenges, homeownership remains a top goal for many Americans. Fortunately, there are ways to turn your dreams of homeownership into reality! In this guide, we’ll explore five common roadblocks to affordable homeownership and actionable solutions to help you overcome them. Let’s break down those barriers so you can finally get the home of your dreams!


ROADBLOCK #1: I Don't Have Enough Saved For A Down Payment


Many prospective buyers believe they need a 20% down payment to buy a home. But in reality, most conventional loans require just 3-5%. And, for buyers who qualify, there are a number of programs and mortgage options that can make a home purchase more accessible.


Down Payment Assistance Programs (DPAs)

DPAs offer grants, loans, and other financial assistance to help with your down payment and closing costs. Many programs are specifically designed for first-time buyers, but there are also options for repeat homebuyers.3,4 These programs can significantly reduce the upfront costs of buying a home. We can help you find down payment assistance programs. Contact us to find out if you may qualify!


0% Down Government-Backed Mortgages
If you qualify for certain government-backed mortgages, you may not need to come up with a down payment at all.
5 While these loans, offered by the Department of Veterans Affairs (VA) and the United States Department of Agriculture (USDA), are not available to all buyers, they offer numerous benefits, including competitive rates and no down payment requirement. 


  • VA loans are available to U.S. military members, including veterans and surviving spouses.6 They do not require a down payment, though the buyer must pay a fee at closing.
  • USDA loans are available to moderate to low-income buyers in certain rural areas.7 They do not require a down payment. 


Family Gifts

Did you know that 25% of first-time buyers in 2024 reported receiving down payment gifts or loans from family members or friends?8 In fact, a growing number of Baby Boomers are choosing to gift all or a portion of their heirs’ inheritance before they pass away.9 Some financial advisors even recommend this as part of their client’s estate plan. Just be sure to follow the proper procedures to document these types of gifts, if you’re fortunate enough to receive them.10


Existing Home Equity

Due to record-high real estate gains over the past few years, if you already own a home, you may have more equity than you realize.11 This equity (or difference between your home’s current value and what you owe on your mortgage) could go toward a down payment on a new property. Wondering how much equity you have in your current home? Reach out for a free home value assessment.


ROADBLOCK #2: I Can't Afford the Monthly Payment


Worried about those monthly mortgage payments? High interest rates and rising costs can make mortgage payments feel daunting. But there are strategies to reduce your monthly burden.


Explore Alternative Mortgage Terms

The traditional 30-year fixed-rate mortgage isn’t the only kind of loan out there. Options like adjustable-rate mortgages (ARMs) or hybrid mortgages can offer lower initial rates.12, 13 Some buyers opt for these if they plan to sell the home before the initial rate term ends or refinance down the road. A lower mortgage rate can significantly lower your monthly payment. However, it’s important to understand the risks involved so you can weigh the pros and cons before deciding.


Consider Discount Points

Buying discount points—a process also known as a permanent rate buy-down—is another great way to limit your monthly costs.14 Essentially, this strategy involves prepaying a fee to lower your interest rate across the life of your loan. If a seller is especially motivated, they may be willing to pay for discount points for the buyer to close the deal on a home. In some cases, we can help you negotiate these types of seller concessions.


Ask About Seller Financing or an Assumable Mortgage

Here are two less common options you might not have considered:15


  • Seller Financing – The seller acts as the bank, offering you potentially better terms than a traditional mortgage.
  • Assumable Mortgage – You take over the seller's existing mortgage with a lower interest rate than what's currently offered by lenders.


Note that these options may or may not be possible for you depending on the seller, the home, and the type of mortgage, but they are worth exploring—and we can help.


Co-Buy with Family or Friends

A growing number of homebuyers are returning to multigenerational living or are even buying a home with friends.16 This arrangement enables you to cut costs significantly while sharing both the time and financial responsibilities of homeownership. We can help you search for homes that are well suited for your group.


Purchase a Home with Income Potential

You can generate extra income to offset your mortgage payments by purchasing a duplex, renting out a room or an accessory dwelling unit (like a garage apartment), or even listing your property on Airbnb. We work with investors and can help you find a property to meet your goals.


ROADBLOCK #3: I Can't Qualify for a Mortgage


Qualifying for a mortgage can be a stressful process, especially if you have previously faced financial challenges. But you might be pleasantly surprised—there’s a lot you can do to improve your chances of success.


Boost Your Credit Score

Your credit score is foundational when it comes to getting a mortgage.17 A higher score typically means a lower interest rate and more options. Take steps to improve your credit by paying bills on time, reducing debt, and checking your credit report for errors. Even a small improvement in your score can make a big difference. Pro tip: Avoid opening or closing credit cards or taking out other loans (like car or personal loans) if you plan to start home shopping in the near future.


Lower Your Debt-to-Income Ratio

Lenders want to see that you can comfortably handle your debts. They assess this by calculating your debt-to-income ratio: your total monthly loan payments (including mortgage, car loans, student loans, and credit cards) divided by your gross monthly salary.18 Paying down other types of debt, like your car loan, will leave more space in your budget for a monthly mortgage payment.


Apply for an FHA Loan

FHA loans are designed for buyers with less access to savings, as well as those with lower credit scores.19 Down payments on FHA mortgages can be as low as 3.5% with a credit score of 580 or above, or 10% with a credit score of 500 or above. Generally, the buyer’s debt-to-income ratio must be below 43%, with no more than 31% of income going to mortgage payments. These loans do come with some additional requirements, such as mortgage insurance (including an upfront premium of 1.75% at closing), a pre-purchase inspection, and borrowing limits that vary based on geographic area.


Consider Getting a Co-Signer

Having a co-signer with a stronger credit history or more income can strengthen your application, but make sure you (and they) understand the risks and responsibilities involved.


ROADBLOCK #4: I Can't Find a Home in My Price Range


Feeling frustrated by the lack of affordable homes on the market? Unfortunately, this is a common problem.20 But with a little flexibility and guidance, it’s possible to find a great property to fit most budgets.


Expand Your Home Search

You may need to search outside your target area. In many markets, home prices vary drastically within the span of miles.21 Being open to exploring alternative neighborhoods or those farther from town can open up surprising possibilities. As local market experts, we can help you discover hidden gems and up-and-coming neighborhoods. Reach out for a complimentary consultation.


Revisit Your Must-Haves

Take a close look at your "must-have" list. Are there any features you can compromise on to expand your options and find a more affordable property? For example, do you really need two bathrooms, or could you settle for a single bathroom with space to add a second one in the future? These types of compromises can sometimes shave tens of thousands off your purchase price. We’re happy to offer our thoughts on the features that you’re likely to find within your budget.
 

Consider Fixer-Uppers

Looking to cut purchase costs? Don't shy away from homes that need a little TLC.22 Fixer-uppers usually come with a lower price tag, and you can personalize the renovations to your taste. Just be sure to factor in the cost of repairs and renovations when determining your budget—and to be realistic about your own home repair skills! If you’re interested in exploring fixer-upper opportunities, we can help you identify properties with potential and connect you with reliable contractors.
 
ROADBLOCK #5: I'm Overwhelmed by the Process


Buying a home can feel like navigating a maze. Between searching for properties, securing financing, negotiating contracts, and handling paperwork, the process can quickly become overwhelming. But you don’t have to do it alone! We can simplify every step, helping you stay organized, informed, and confident in your decisions.


Find the Right Home Faster

The sheer number of listings on the market can be daunting, and homes that meet your criteria may not always be easy to find. Our team can:


  • Save you time by narrowing down homes that fit your budget, needs, and lifestyle.
  • Get you access to off-market and pre-listing properties that aren’t widely advertised.
  • Provide insights on local market trends to help you make a competitive offer.


Navigate Financing & Paperwork With Ease

Real estate transactions involve complex contracts, legal documents, and lender requirements. One misstep could delay your purchase—or even cost you your dream home. We will:


  • Help you find down payment assistance or grants that you may not be aware of.
  • Explain mortgage options and connect you with reputable lenders.
  • Ensure all purchase documents are accurate and deadlines are met.


Score the Best Deal

Many buyers worry about overpaying for a home or getting stuck with costly repairs, but we know how to:


  • Use expert negotiation tactics to secure the best possible price.
  • Identify hidden costs so you aren’t caught off guard at closing.
  • Negotiate repairs or seller concessions to save you money.


Streamline Inspections & Closing

The home inspection and closing process can bring last-minute surprises. We avoid these by:


  • Helping you interpret inspection reports and advising on necessary repairs.
  • Coordinating with lenders, appraisers, and title companies to keep everything on track.
  • Preparing you for closing day so you know exactly what to expect.


Benefit From Ongoing Support

Our relationship doesn’t end once you get the keys. We always go the extra mile to:


  • Recommend trusted contractors for renovations and repairs.
  • Help you make strategic upgrades through complimentary real estate consultations.
  • Provide market updates in case you want to refinance or sell later.


The bottom line? You don’t have to navigate this process alone. When you work with us, you’ll have a trusted partner to handle the complexities, answer your questions, and ensure everything goes smoothly from start to finish.


LET’S TURN ROADBLOCKS INTO STEPPING STONES TOWARD YOUR DREAM HOME


Buying a home may come with challenges, but none of them are impossible to overcome. With the right strategies, resources, and expert guidance, you can navigate these obstacles with ease.


Whether you're worried about saving for a down payment, qualifying for a mortgage, or finding the right home in your price range, there are solutions available to help you move forward. The key is to stay informed, explore all your options, and work with professionals who can guide you every step of the way.


Our team is here to help you find the right home, secure the best financing, and negotiate the best deal—without the stress and uncertainty of doing it all yourself. Let’s turn your homeownership dreams into reality. Contact us today to get started!


The above references an opinion and is for informational purposes only. It is not intended to be financial, legal, or tax advice. Consult the appropriate professionals for advice regarding your individual needs.


SOURCES:

1.    Bankrate - 
https://www.bankrate.com/mortgages/home-affordability-report/#unaffordability

2.    Nerdwallet - 
https://www.nerdwallet.com/article/mortgages/2025-home-buyer-report

3.    Bankrate - 
https://www.bankrate.com/mortgages/first-time-homebuyer-grants/#types

4.    Down Payment Resource - 
https://downpaymentresource.com/

5.    Bankrate - 
https://www.bankrate.com/mortgages/types-of-mortgages/#government-backed

6.    Bankrate - 
https://www.bankrate.com/mortgages/understanding-va-loans/

7.    Bankrate - 
https://www.bankrate.com/mortgages/what-is-a-usda-loan/

8.    National Association of Realtors - 
https://www.nar.realtor/research-and-statistics/research-reports/highlights-from-the-profile-of-home-buyers-and-sellers

9.    Business Insider - 
https://www.businessinsider.com/boomers-not-waiting-pass-inheritance-wealth-transfer-millennials-need-it-2024-7

10.  Experian - 
https://www.experian.com/blogs/ask-experian/down-payment-gift-rules/

11.  Bankrate - 
https://www.bankrate.com/home-equity/homeowner-equity-data-and-statistics/

12.  Nerdwallet - 
https://www.nerdwallet.com/article/mortgages/adjustable-rate-mortgage-arm

13.  Lending Tree - 
https://www.lendingtree.com/home/mortgage/what-is-a-hybrid-mortgage/

14.  Investopedia - 
https://www.investopedia.com/terms/d/discountpoints.asp

15.  Lending Tree - 
https://www.lendingtree.com/home/mortgage/what-to-know-about-owner-financing/

16.  National Association of Realtors - 
https://www.nar.realtor/blogs/economists-outlook/home-for-the-holidays-the-rise-of-multi-generational-home-buying

17.  Consumer Financial Protection Bureau - 
https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/

18.  Nerdwallet - 
https://www.nerdwallet.com/article/mortgages/debt-income-ratio-mortgage

19.  Bankrate - 
https://www.bankrate.com/mortgages/what-is-an-fha-loan/#requirements

20.  Bankrate - 
https://www.bankrate.com/real-estate/low-inventory-housing-shortage/

21.  Realtor - 
https://www.realtor.com/advice/buy/priced-out-of-dream-neighborhood-cheaper-alternative/ 

22.  This Old House - 
https://www.thisoldhouse.com/buying/21017198/buying-a-fixer-upper-house
September 4, 2026
For most of the internet era, searching for a home meant the same ritual: set your price cap, pick a number of bedrooms, check a few boxes, and scroll. Then the real work started — sifting through pages of results, opening listing after listing, digging for the details that actually mattered. That ritual is quietly starting to give way. Today, a fast-growing share of home searches begin as a conversation: someone typing "find me a home where my mom could live with us, near a park, under our budget" into an AI assistant and getting real answers back. Nearly half of prospective buyers now say they're using AI tools somewhere in the homebuying process.¹ And this isn't happening off in a corner of the tech world. In late 2025, Zillow became the first real estate app built directly into ChatGPT. Actual listings, with photos, maps, and prices, now surface inside the chat itself.² The other major portals have followed with AI search of their own.³ The biggest names in home search have decided the conversation is the new front door. If that sounds like a big shift, it is: roughly the size of the move from newspaper listings to online portals a generation ago. In many ways, it's making the home search easier. But these tools also come with a few things worth watching for. So here's what they're genuinely good at, where they get things wrong, and what the change means whether you're buying or selling. How AI Makes the Home Search Easier Treated as a research assistant, AI is genuinely excellent at the early, wide-open stage of a home search. Start with the search itself. You don't have to translate your life into filter categories anymore; you can describe the life and let the machine translate. "We need space for a home office, my in-laws stay for a month every winter, and I can't do a long commute" is now a workable query. Better still, the conversation continues from there: "more like this one, but with a yard." "What's the tradeoff between these two?" "Which one has the shorter drive to downtown?" The sifting that used to mean twenty open tabs and a lost Saturday? That part, the machine now does. It's also a patient explainer. Escrow, contingencies, HOA rules, points, loan types: you can ask what anything means, at midnight, without feeling like you're asking a dumb question, and keep asking follow-ups until it's actually clear. And it's quick with the math and homework that used to slow everything down. Among buyers using AI, 57% use it to estimate affordability, mortgage payments, or closing costs, and about half use it to research neighborhoods, market trends, or property values.⁴ Rough monthly-cost scenarios that once took a spreadsheet and an afternoon now take minutes, which means you can test more possibilities before committing to any of them. Add it up, and the fog-clearing phase of a home search — figuring out what you actually want, what it costs, and where to look — moves dramatically faster than it did even two years ago. That phase is real work, and this is the stuff AI is genuinely good at. Where AI Gets It Wrong — and How to Catch It AI's failure mode is being confidently wrong : it delivers mistakes in the same fluent, assured tone as facts, and it doesn't flag when it's guessing. Sometimes that means hallucination, the industry's word for AI inventing things: details, listings, even whole answers that sound polished, specific, and true but aren't. Sometimes it just means stale information, like a recommendation built on a home that sold three weeks ago. Then there's a second category, and it matters more: the things AI can't see at all. Condition. It can't see the true condition of the home, or of the competing homes its price comparisons quietly rest on. Feel. It doesn't know how a street actually lives: what it sounds like at rush hour, how it feels on a Saturday morning. School lines. One side of a street can feed a more desirable school, or a standout principal. The map data AI reads won't tell it that. Position. A corner lot and a home tucked deep in the cul-de-sac can carry very different values. AI reads them as the same address. What hasn't been announced. The empty field nearby that's likely to be developed, the rezoning that's still a rumor at the county office: these shape future value, and they live in local knowledge, not datasets. And those are examples, not the whole list. Every neighborhood carries its own intangibles: the plans, reputations, and quirks you only learn by being there, or by talking to someone who has. No portal or chatbot has a column for them. None of this makes AI the wrong tool; it makes verification part of using it well. Treat its answers as leads rather than conclusions, and check anything you'd act on against the live listing, the disclosures, or someone who's actually been inside. You wouldn't make one of the largest financial decisions of your life on a single unverified source in any other context. This is no different. Selling? Your Home's First Showing Is Now to a Machine If you're on the other side of the transaction, the same shift reaches you in a way most sellers haven't considered: before a buyer ever sees your photos, an AI may have already read, summarized, and ranked your listing. When listings surface inside a chat conversation, software is doing the first sort.² Your home either comes up in that conversation or it doesn't, and what decides that is the substance of the listing: the real upgrades, the real layout, the real numbers. Specific, accurate details are what machines can find and repeat. Vague lifestyle copy is what they skip. It also means your photos and your facts need to agree. An AI summary will amplify an inconsistency that a human browser might have skimmed right past. And pricing right matters even more than it used to, because a mispriced home gets quietly filtered out of conversations it never knew were happening. None of this is a crisis — it's a presentation shift. Sellers who understand how homes get found now have a real edge over sellers whose listings are still written for 2019. It's worth asking whoever lists your home how it will read to both audiences: the buyer, and the machine summarizing it for the buyer. What Hasn't Changed (and Won't) AI is at its best in the research phase: gathering, comparing, explaining, estimating. The decisions that determine how the whole thing turns out (what to offer, how to negotiate, when to walk away, how to price) are a different kind of work, and they still come down to judgment. Pricing strategy, offer strategy, and negotiation are calls built on local, current, in-person knowledge. AI can assist the analysis, but it has never walked the block at 6 p.m., smelled the basement, or heard what the neighbors said at the open house. And a home purchase is a life decision wearing a financial costume; a good agent helps you manage both, and a chatbot manages neither. Buyers seem to understand this instinctively. Even as AI use climbs, 88% of buyers still purchased their home through an agent or broker.⁵ And 44% of consumers say they'd pay more for a professional to verify what AI told them.⁶ That instinct is right. An agent's edge is precisely the list of things AI can't see: condition, feel, school lines, lot position, what's about to be built next door. The Smart Way to Run an AI-Assisted Home Search (or Sale) Put it together and it's a simple division of labor. If you're buying: use AI to sharpen your wish list, learn the vocabulary, rough out affordability, and build a candidate list. Then bring that homework to a person who can verify it, tour with you, price it, and negotiate it. If you're selling: ask your agent how your listing reads now, to buyers and to the machines briefing them, and make sure the details and the price can survive both audiences. Either way, what AI actually buys you is speed, clarity, and convenience: answers in minutes instead of weekends, a complicated process explained in plain language, help available whenever you're thinking about it. The numbers already tell the story of how this really works: about half of buyers now start with AI,¹ and 88% still finish with a person.⁵ Let the machine do the homework, and keep a person on the decision. If AI has been part of your home search, or you're wondering how your home would look through its eyes, reach out. Bring me what the chatbot told you, and I'll tell you what it got right. Sources  1. 2026 Home Buyer Report — NerdWallet (The Harris Poll, Nov 2025) 2. Zillow becomes the only real estate app in ChatGPT — Zillow, Oct 6, 2025 3. Realtor.com the latest portal to launch search app in ChatGPT — Real Estate News, Mar 30, 2026 4. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Bank of America Homebuyer Insights Report) 5. 2025 Profile of Home Buyers and Sellers — National Association of REALTORS® 6. AI Becomes Early Step in Homebuying Journey — National Association of REALTORS®, Jun 30, 2026 (Cotality consumer survey)
August 5, 2026
For the past two years, a lot of people have been waiting on the housing market to do one specific thing: drop rates dramatically and "unfreeze." That was the plan for buyers and sellers alike. I'll move when rates come down. That big drop never fully arrived. And the market changed anyway. It didn't unfreeze. It thawed — slowly. Halfway through 2026, buyers in many markets have more homes to choose from, more time to decide, and more room to negotiate than they've had in years. Sellers are adjusting to a slower, more selective market. It's not a perfectly balanced market everywhere. But compared to the pandemic-era bidding wars, and the frozen, locked-up market that followed them, it looks a lot more balanced. Nobody rings a bell when a market becomes more negotiable. Booms and crashes make headlines; a market quietly returning to normal doesn't. So consider this your mid-year bell: here's what the first half of 2026 actually tells us, and what it means whether you're buying, selling, or staying put. More Homes, More Time, More Conversation Start with what changed. There are meaningfully more homes on the market than during the low-inventory years: about 1.56 million listings nationally as of June, or 4.6 months of supply.¹ That's not a glut, and the growth has been leveling off as some would-be sellers step back rather than chase the market. But for buyers who spent years picking from slim inventory, it's a real difference. And the market isn't frozen. Sales bounce around from month to month, but they're running ahead of where they were a year ago.¹ People are moving without the dramatic rate drop everyone was waiting on. The bigger shift is in how deals come together. Negotiation is a standard part of the process again. Nearly half of sellers, 46% in May, gave buyers some form of concession, a record for that month.² Price reductions are far more common than they were during the frenzy. For buyers, that's a signal of how negotiable this market is, not necessarily a problem with the home. Inspections, repairs, closing costs, timing: these are conversations again, not sacrifices you make to win a bidding war. More negotiation doesn't mean buyers control every market. A well-priced home in a tight area can still sell fast, sometimes with competition. What it means for you: if you're buying, the list price is no longer the whole conversation. A reduced price is often an invitation to look closer, not a reason to stay away. If you're selling, the lesson runs the other way: strategy matters more than optimism. The goal is to price right on day one so you never need the cut. Homes that reduce are usually correcting a pricing decision the market already voted on. Rates Are No Longer the Only Story Mortgage rates spent the first half of the year drifting rather than diving. The average 30-year fixed rate was 6.49% in mid-July, a shade better than the 6.72% from a year ago, but nowhere near the dramatic relief people were holding out for.³ The market improved anyway. Affordability has quietly been getting better. Buying power stretches a little further than it did a year ago, as income growth outpaces home-price growth in most of the country.¹ Not dramatically. Cumulatively. And the people transacting in 2026 aren't necessarily the ones who timed the market perfectly. They're the ones whose lives changed: a new job, a growing family, a downsize, a divorce, a retirement, a relocation. Life decisions, not rate decisions, are driving moves again. Waiting has a cost too. I've watched plenty of buyers hold out for a rate that never arrived while their needs kept changing, like the family that outgrew their space two years ago, or the retiree maintaining a house that stopped making sense. If the only thing keeping you on the sidelines is a number, it's worth running the math on what waiting is actually costing you. What it means for you: rates still shape affordability, but they're not the whole plot anymore. Price, concessions, inspection terms, timing, and the right property all shape the outcome too. You can't control the rate — you can control almost everything you negotiate around it. What the National Numbers Can Miss The national market barely exists. Conditions differ sharply by region, price point, and property type. Some markets have tipped genuinely toward buyers, with more listings, longer timelines, and real leverage. Others remain stubbornly tight, with limited supply and quick sales. Even price direction is diverging: some regions are still posting solid annual gains while others have flattened out.¹ Two buyers with similar budgets can have completely opposite experiences depending on where and what they're shopping for. The national median price tells the same story in one number: $440,600 in June, up just 1.8% from a year ago.¹ A modest gain, but that one number is an average of markets moving in different directions. This is exactly where the gap between the headline and your street gets expensive. What it means for you: national headlines tell you the direction of the market. They can't tell you what your home is worth, what your competition looks like, or how much negotiating room exists in your neighborhood. Only a local read can. What It Means for You — Buyers, Sellers, and the Staying-Put A more balanced, more local market rewards preparation over timing. What that looks like depends on whether you're buying, selling, or staying put. If you're buying: you have more choice and, in many markets, more leverage than you've had in years. Use the time this market gives you: inspect thoroughly, negotiate genuinely, and compare concessions, not just list prices. A seller-paid rate buydown or closing-cost credit can sometimes do more for your monthly payment than a modest price cut. First-time buyers are finding more entry points than they have in years, making up 33% of June's buyers¹, but affordability still requires discipline. More options doesn't mean easy. If you're selling: you can absolutely still win in this market. But pricing right from day one, presenting well, and expecting negotiation are now the job description. "Testing the market" with an ambitious price costs real time and real money. The homes that sit are usually the ones that priced for 2021. If you're staying put: a calmer market is a good moment for a low-stakes check-in. What's your home worth now? What does your equity look like? Does this home still fit your life? No urgency, just awareness. The forecast for the second half of the year calls for modestly better sales, not fireworks⁴, which means this planning window stays open. Across all three: the second half of the year favors people who know their local numbers, not people waiting for a national signal. Balance doesn't pick winners. Preparation does. The Second Half Belongs to the Prepared That's the mid-year picture: more choice, steadier rates, more negotiation, and conditions that are sharply local. For the first time in a while, this is a market you can plan in rather than react to. The national story is the easy part — you just read it. The part you can't Google is what it means on your street, for your home, on your timeline. If you're wondering what this market means for your specific situation, reach out. Whether you're thinking about buying, selling, or just want to know where your home stands, that's exactly the kind of conversation I'm happy to have, no pressure attached. Sources 1. Existing-Home Sales Report, June 2026 — National Association of REALTORS® 2. 46% of Home Sellers Gave Concessions to Buyers in May — Redfin 3. Primary Mortgage Market Survey, July 9, 2026 — Freddie Mac 4. NAR Chief Economist Lawrence Yun: Home Sales Expected to Improve in Second Half of 2026 — National Association of REALTORS®
July 1, 2026
When most people picture negotiating on a home, they picture one number: the list price. You offer somewhere under the asking price, the seller counters, you settle in the middle, and whoever gives up the most ground "loses." For a lot of buyers, that back-and-forth over the sale price is the negotiation. It's only a fraction of it. The price is the headline. The real negotiation happens in the terms underneath it, and right now those terms are where the money is. Buyers have more room to ask than they've had in years. The market has tilted in their favor, and it's showing up at the closing table: in 2025, 62.2% of buyers paid below the list price, and the typical below-list buyer saved 7.9% — about $31,592 — the biggest discount in over a decade.¹ So here's what actually separates the buyers who come out ahead. It isn't the ones who push hardest on the price. It's the ones who understand everything that's on the table, and know which things are worth asking for. The Price-Only Trap It's easy to assume a seller cares about one thing: the highest possible number. In practice, most care about more than that. They care about certainty, meaning whether the deal will actually close. They care about timing. They care about whether your financing will hold together or fall apart three weeks in. That matters for you, because it means you have more to work with than a single figure. A buyer who treats the offer as a package — price, terms, timing, and risk all together — can often create a better outcome than a buyer who just hammers on price and calls it a day. That's why a clean, well-structured offer can beat a higher one: to the right seller, the certainty is worth more than the extra dollars. So before you anchor on a number, widen the lens. Here's what else is on the table. The Money Levers Beyond the Price Some of the most valuable things you can ask for never touch the sale price at all. They change what you actually pay out of pocket. Start with a seller concession. This is money the seller agrees to credit you at closing, most often to cover part of your closing costs, which typically run 2% to 5% of the purchase price.² Rather than cutting the sale price, the seller puts cash toward those costs, lowering what you need to bring on closing day. It's worth asking for any time your upfront cash is the tightest constraint, which for a lot of buyers it is. And it's far from a long shot right now: about 44% of sellers recently gave buyers a concession of some kind, close to the highest share on record.³ A rate buydown is one of the least understood levers, and one of the most valuable. When you buy down the rate, someone pays the lender an upfront sum in exchange for a lower mortgage interest rate. In a negotiation, you ask the seller to be the one who pays it. A buydown can be permanent, lowering your rate for the life of the loan, or temporary. A common version, the "2-1 buydown," cuts two percentage points off your rate the first year and one point the second, then settles at the full rate. Builders have leaned on this hard: 64% were offering incentives like buydowns and closing-cost help earlier this year.⁴ It's worth understanding why this can beat a price cut outright. Take $10,000 off the sale price and your monthly payment barely moves, maybe a few dollars on a 30-year loan. Put that same $10,000 toward buying down your rate, and you feel it in every payment for as long as you own the home. It's the same money out of the seller's pocket, but a far bigger result in yours. The Inspection Is Your Second Negotiation Most buyers treat the home inspection as a hurdle to clear: pass it, and you move on. It's better understood as a second negotiation, and the leverage is usually built in, because an inspection on almost any home turns up something worth addressing. When it does, you generally have two options. You can ask the seller to make the repairs before closing, or ask for a credit instead so you can handle the work yourself afterward. The credit is often the cleaner win. You control the contractor, the timeline, and the quality of the work, instead of depending on a seller's rushed, last-minute fix. A few rules of thumb. Focus on what genuinely matters, meaning health, safety, and the big-ticket systems like the roof, HVAC, or foundation, rather than nickel-and-diming every cosmetic flaw. Consider asking for a home warranty to cover the things that tend to break after you move in. And treat the report as a planning tool, not just a bargaining chip. A fifteen-year-old water heater isn't a reason to walk away. It's a heads-up that helps you budget. Terms and Timeline: The Wins That Aren't About Money One of the most powerful levers costs you nothing: flexibility. To a seller, time is often worth as much as dollars. Say the sellers need a few extra weeks in the home because their next place isn't ready. Offering a rent-back, which lets them stay on for a short period after closing, can make your offer the one they choose even over a higher bid. Or maybe they need to close fast, and you're in a position to deliver. The closing date, the possession date, the length of your contingency periods, even how your earnest money is structured: all of it is something you can shape. The strategic move is simple. Give the seller the timeline they need, and you'll often get the terms you want in return. What Actually Comes With the House This is the simplest ask of all, and the one buyers most often forget to make: what physically stays with the house. Appliances, window treatments, the mounted TVs, the washer and dryer, sometimes even furniture or the patio set you admired during the showing. A lot of it is negotiable. The law draws a line between fixtures, which are generally included, and personal property, which generally isn't, and that line is exactly where a quick ask can pay off. One rule matters above the rest: get every extra written into the contract. A friendly "sure, we'll leave the fridge" during a showing means nothing if it isn't on paper. And if there's something you want, ask for it. The worst answer you'll get is no. How to Actually Use the Whole Menu Knowing what's negotiable is the easy part. Using it well is what turns a list of asks into a better deal. The buyers who succeed don't fire off every possible demand at once. They lead with what the seller values most, group their requests thoughtfully, and avoid the death-by-a-thousand-cuts approach that makes a seller dig in. Above all, they read the seller's real motivation, and that's where a skilled agent earns their keep. It's no accident that 88% of buyers work with an agent, and that the help they value most is negotiating the terms of the deal.⁵ A calm, well-prepared buyer with a clear strategy almost always does better than an aggressive one throwing elbows. The goal isn't to beat the seller. It's to structure a deal that works for both sides, and to make sure you're not leaving value on the table you never knew was there. If you're getting ready to buy, this is exactly the kind of thing worth talking through before you write an offer. I'm glad to walk through everything you could be asking for in your particular situation. No pressure, just a clear picture so you can make a confident decision. Sources Redfin — Homebuyers Are Scoring the Biggest Discounts in 13 Years Redfin — What Are Closing Costs and How Much Will You Pay? Redfin — 44% of Home Sellers Are Giving Concessions to Buyers NAHB / WTOP — Builder Incentives and Rate Buydowns NAR — 2025 Profile of Home Buyers and Sellers